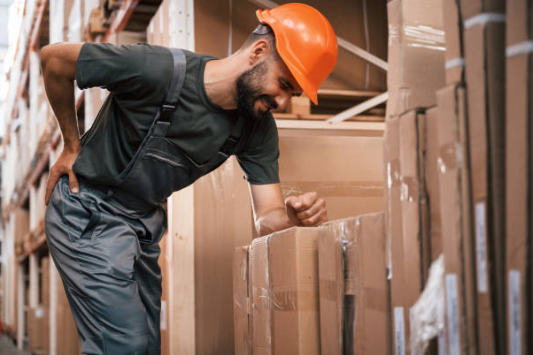
If a handyman is injured on your property and the medical costs exceed their insurance coverage, the person or business responsible for the accident may have to pay the remaining damages. However, a property owner is not automatically liable just because the injury happened at their home. Responsibility depends on how the accident occurred, whether the owner acted negligently, the handyman’s employment status, and the insurance policies involved.
Knowing what to do if a handyman gets hurt on your property can help you understand your potential financial exposure before a dispute becomes more serious. The key is to determine who caused the accident, what insurance applies, and whether the injured worker has grounds to pursue additional compensation.
When the Property Owner May Be Responsible
Property owners generally have a duty to take reasonable steps to address dangerous conditions they know about or should reasonably discover. If a handyman trips over a broken step that the owner knew was unsafe but failed to disclose, the owner could face a negligence claim.
The same issue may arise when an owner asks a handyman to work in an unsafe area without warning about a known hazard. Depending on the circumstances and local law, a court may consider whether the owner failed to provide a reasonably safe environment.
On the other hand, a handyman who ignores clear warnings, uses equipment improperly, or creates the hazard may bear some or all of the responsibility. The final outcome depends on the available evidence and the rules governing the claim.
How Insurance Coverage Is Applied
Several types of insurance may become relevant after a handyman is injured.
The handyman’s own coverage: An independent contractor may carry general liability insurance, but that policy primarily covers liability for injuries or property damage the contractor causes to others. It does not necessarily cover the handyman’s own medical bills. Contractors may need health insurance, workers’ compensation coverage where applicable, or other protection for their injuries.
Workers’ compensation: If the handyman is an employee, workers’ compensation may cover qualifying medical expenses and part of their lost wages. Coverage requirements vary by state, industry, and employer size. Calling someone an independent contractor does not always settle their legal employment status.
The property owner’s liability insurance: A homeowner’s insurance policy may cover certain claims alleging that the owner’s negligence caused an injury. Coverage depends on the policy language, exclusions, and facts of the incident.
Umbrella insurance: An umbrella policy may provide additional liability protection after an underlying policy’s limits are exhausted, but only if the claim falls within its coverage. It does not automatically cover every accident on the property.
What Happens When the Costs Exceed the Policy Limits
Imagine a handyman suffers a serious fall and requires surgery, rehabilitation, and months away from work. The total damages could exceed the available insurance limits.
If the property owner is legally liable, the injured worker may seek the uncovered amount directly from the owner. This could involve negotiations, a lawsuit, or a settlement. However, a large medical bill alone does not prove that the owner owes the money.
State laws can affect how liability is decided. For example, California Civil Code § 1714 generally addresses responsibility for injuries caused by a person’s lack of ordinary care. Whether it applies to a particular accident depends on the facts and other relevant legal rules.
Steps to Protect Yourself After an Injury
Act promptly if a handyman is hurt on your property. Arrange appropriate medical assistance, document the accident scene, and preserve photographs, contracts, messages, and witness details. Avoid altering the scene before relevant evidence is recorded, unless changes are necessary to prevent further harm.
Notify your insurer as soon as possible and provide accurate information about what happened. Do not assume the contractor’s insurance will cover every expense, and avoid making promises about payment before liability and coverage are reviewed.
If the injuries are serious or the insurer disputes coverage, consider seeking legal advice. A qualified attorney can assess the evidence, applicable state law, and potential insurance sources.
Key Takeaways
- A property owner may be responsible for uncovered damages if their negligence caused the handyman’s injuries.
- A handyman’s liability insurance may not cover their own medical expenses.
- Workers’ compensation, homeowners’ liability insurance, and umbrella coverage may apply depending on the circumstances.
- Policy limits do not automatically determine who is legally responsible.
- Document the incident, notify the insurer promptly, and review the relevant policies before agreeing to pay a claim.